
Raising money feels like a milestone. Sometimes it is. Other times it’s an expensive fix for a problem a better budget could have solved.
TL;DR: Before you pitch a single lender or investor, get clear on what the money is for, whether your own cash flow can cover it, what you’re willing to give up, and whether your books can survive a close look.
Why So Many Owners Raise Too Early
I’ve sat across the table from a lot of owners who wanted to raise. Some needed it. Plenty didn’t. They just assumed growth required a check from someone else.
It’s easy to see why. Funding announcements get the headlines. Nobody writes a press release about the company that grew quietly on its own profits. But taking on outside capital changes your business in ways that are hard to undo, so it’s worth slowing down for a minute.
4 Questions to Ask Before You Raise
What Exactly Will the Money Do?
“Growth” isn’t an answer. Hiring three salespeople is. Buying a second production line is. If you can’t tie the money to a specific result and a rough timeline, you’re not ready yet. Investors will ask anyway, so you might as well know first.
Can Your Own Cash Flow Cover It?
This one stings a little. A lot of funding gaps are really cash management gaps: slow collections, bloated inventory, pricing that hasn’t moved in five years. Fix those and you might find the money was already sitting in your business. Still short? A line of credit or an SBA-backed loan can bridge the gap without selling a piece of the company. Our breakdown of the best financing options for small businesses walks through the tradeoffs.
What Are You Willing to Give Up?
Every dollar has a price. With debt, it’s interest and a monthly payment, good month or bad. With equity, it’s ownership, a cut of future profits, and usually a voice in big decisions. The U.S. Chamber’s guide to equity vs. debt shows how your stage and cash flow tip the scale. Be honest here. If the thought of a board vote makes your stomach turn, equity probably isn’t your path.
Are Your Financials Ready for Scrutiny?
Lenders and investors will go through your numbers line by line. Messy books, no forecast, a story that shifts every meeting? Deals die over that stuff. And credit isn’t exactly easy for smaller firms right now, as the Federal Reserve’s latest report on small employer firms makes clear. Our guide on how to prepare for capital raising covers what to have in place before that first meeting.
So When Does Raising Actually Make Sense?
When the money has a clear job, your internal options are tapped out, you understand the tradeoff, and your numbers hold up. That’s when outside capital becomes a tool instead of a crutch.
At that point, the next question is whether to run the process yourself or bring in an advisor to help you raise. For bigger raises, it gets complicated fast (and a fractional CFO can keep your forecasts honest the whole way through).
A Final Word from Someone Who’s Been There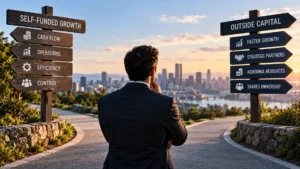
Raising money isn’t a badge of honor. It’s a decision. The best owners I’ve worked with treat it like any other big purchase: they know what they’re buying, what it costs, and what they expect back.
If you’re weighing whether outside capital is the right move, talk it through before you commit. Surfside Capital Advisors helps Boston-area and national businesses raise capital, plan exits, and make smarter financial calls. Give us a call at 617 830 7225 for a straight conversation about your options. No pressure, just clarity.
