
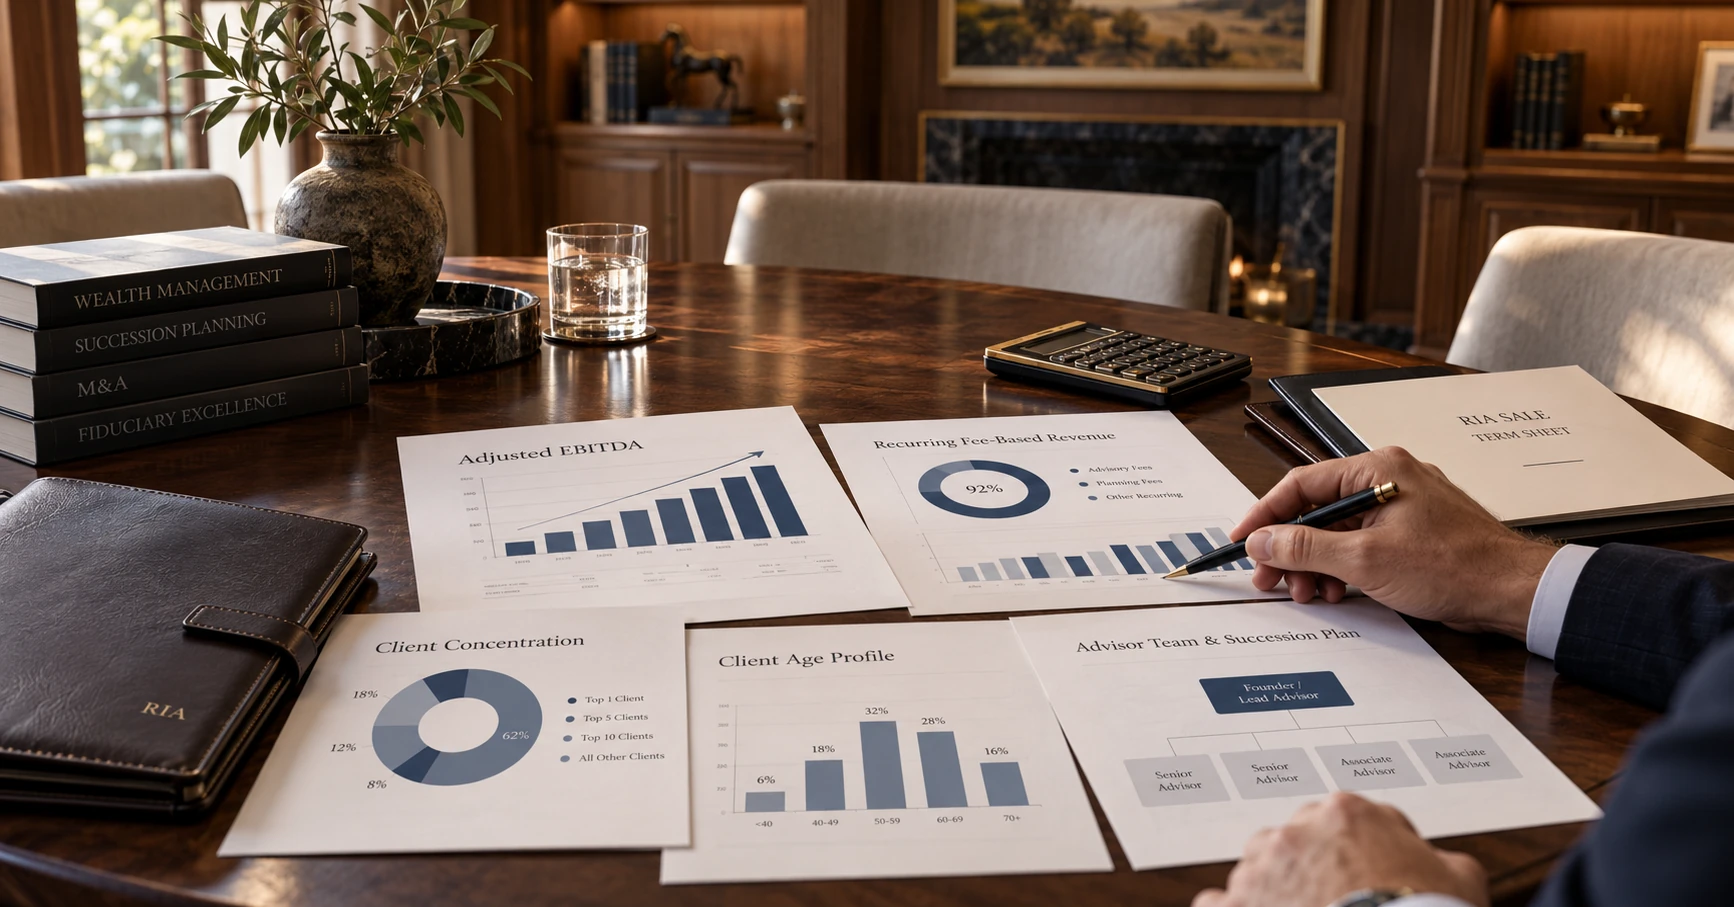
So you’re thinking about selling. Maybe retirement’s calling, maybe a bigger firm made an offer hard to ignore. Either way, before you sign anything, you need to know what your firm is worth.
TL;DR: To value your RIA before a sale, focus on your adjusted earnings, not your revenue. That multiple swings hard based on growth, client concentration, and how well the business runs without you in every meeting.
What Actually Determines How Buyers Value an RIA
If you want to value your RIA before a sale with any accuracy, start here: size matters less than you’d think. A $300 million firm with an aging client base can be worth less than a $150 million firm growing 15% a year. Buyers underwrite the future, not your past.
What moves the needle:
- Organic growth. Net new assets, not market bumps, not a lucky acquisition.
- Recurring, fee-based revenue. Ideally 90% or more. Commissions make buyers nervous.
- Client concentration and age. A handful of large, elderly clients is a risk.
- Next-gen bench strength. If you disappear tomorrow, does the firm survive?
- Clean books and documented processes. Boring, I know. It’s also what closes deals.
EBITDA vs. Revenue Multiples: Which One Applies to You?
Smaller, owner-operator shops usually get valued on seller’s discretionary earnings, cash flow before your own paycheck. Once you’ve got non-owner advisors with real client relationships, buyers shift to adjusted EBITDA, with your pay normalized to market rate.
Headline multiples in the high teens grab attention, but a lot of that number sits in earn outs you may never fully collect. Those “terms traps” are worth understanding before you get excited about a number, because the real offer is often smaller than the press release version.
Why Do Similar-Sized Firms Get Such Different Offers?
Because buyers, especially private equity backed aggregators, aren’t just buying AUM. They’re buying culture fit, growth trajectory, and reduced key-person risk. Understanding what large buyers actually weigh before making an offer saves you from walking into a negotiation blind (trust me, sellers who skip this step leave money on the table).
It’s also worth knowing your structure going in. If you haven’t settled the RIA vs. broker-dealer question for your business, that’s a conversation to have before, not during, a sale process.
How Can You Boost Your Number Before You List?
You don’t need years to value your RIA before a sale differently. Twelve to eighteen months of focused work can shift where you land in your band. We’ve written before about the specific moves that increase business value before an exit, and most of it boils down to profitability, documentation, and reducing how much the business depends on you.
Founders also repeat the same errors here: overestimating comparable multiples, misreading what drives valuation, being too close to see the weaknesses. We broke down the most common valuation mistakes founders make, and honestly, most are avoidable with a little planning.
When Should You Bring in an Advisor?
Earlier than you think. The gap between what sellers expect and what buyers actually pay is a well documented problem in this industry, and a leading reason deals fall apart mid-negotiation. You need someone who’s done this before and isn’t attached to your rosy projections.
Final Thought
I’ve sat across the table from enough owners to know this: the best outcomes go to firms that started preparing two years early and asked hard questions before a buyer ever did. If you’re serious about how to value your RIA before a sale, don’t wait until a term sheet is on the table. That’s the worst time to start asking.
Ready to figure out what your firm is really worth? Work with our team at Surfside Capital Advisors and get a straight answer, not a sales pitch.
